Wednesday, March 14, 2012

A Closer Look at January's Vegas Jobs Report

When I compiled the draft numbers for our first quarter reports last week, I was a bit stunned. I had been expecting a weak quarter, but not that weak. Now that I’ve seen the new employment numbers from the Nevada Department of Training, Education and Rehabilitation, I’m not so shocked.

I’ve seen some stories touting the drop in the unemployment rate, but a real delve into the numbers reveals a job market that started the year off by shrinking, with weak numbers across the board, not just in retail where one might expect a drop after the temporary hires for the holiday season.

For Las Vegas, the traditional important numbers have been Leisure & Hospitality - the engine of growth - Construction and Retail. Those are the meat and potatoes.

Leisure & Hospitality (L&H) saw a big boost in employment towards the end of last year which boded well for some more substantial recovery in mid- to late 2012, as those new jobs increased hiring in the wider retail sector, which creates jobs in other sectors, etc. Along come the January 2012 numbers and we see L&H taking a slight breather and giving back a few jobs. Until we see some February numbers float by, we can't call this a trend, but a continuation of the boost would have been more welcome.


Construction is an old story by now, fit for a VH1 Behind the Music episode. A meteoric rise as cheap money drove people into new homes and then an equally meteoric fall in 2008. The last few months, however, have seen the fall become less meteoric, and there were even a couple months in there where month-over-month construction employment increased. And then, once again, we see January numbers and we're back to the bad old days. Again, we can't call this a trend, but it's a painful development when one's optimism was just beginning to return.


The employment sectors that are most important to commercial real estate were universally bad when looking at quarter-over-quarter numbers (okay, except for Wholesale) ...


But not entirely bad when looking at year-over-year numbers, with Retail showing some strength, along with Transportation & Warehousing (linked with retail sales), Wholesale (linked with retail sales) and Manufacturing. The office sector is getting killed, though, and a cessation of growth in the Healthcare sector is a little distressing.


Still, when you look at the employment index (Jan 2006 = 100), you really don't see a recovery you can write home about.
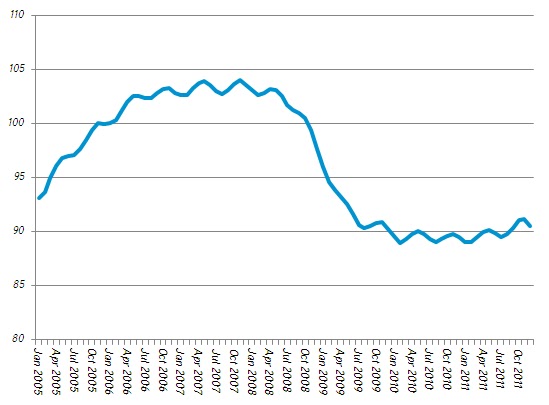

As I’ve said many times, jobs and net absorption are tied pretty close, as this graph illustrates.


All in all, not the best way to start a year that already has some significant headwinds to throw against our sails. Let's see what February's numbers teach us.

Monday, February 27, 2012

Hot & Cold - Mapping Asking Rents in Southern Nevada

My project today was to map asking rents in Southern Nevada using a rent index.

Click for a larger map

The key with rents, of course, is that are highly variable between different product types. While Class A Office product can pull in $3.00 per square foot (psf) on a monthly basis, warehouse pulls in maybe $0.30 psf. To smooth out the differences, I decided to index asking rents for each product type based on the weighted average for that product type in the fourth quarter of 2011. Thus, a warehouse space that was asking the same as the average asking rent for warehouse would be indexed as a "1"; anything asking more would have an index number of higher than 1 and anything lower would have an index number lower than 1. By indexing the availabilities in the database, I can compare different product types on the map above.

The map above ignores anything at or near an average asking price. For the purposes of this map, they are just added noise. Screening them out, we can see some regions of Southern Nevada in terms of how much landlords are asking for rent.

The highest asking rental rates appear to wrap around the west and south portions of the Valley, while lower asking rents predominate in the east, center and north portions. This makes sense. The west and south feature newer construction, while the center and east feature older construction. One might deduce from this map, then, that newer properties command higher rents than older properties, and perhaps they are right. Then again, perhaps they are wrong.

The values on this map are based on "asking" rents, not actual rents. The proof in the pudding is in the taste, and the proof in the asking rents is in the absorption. The question, then, is this: Are those high asking rates scaring prospective tenants away, or are tenants still willing to pay more for the more expensive, newer buildings?

On a submarket basis, combining office, industrial and retail properties, net absorption in 2011 broke down as follows:

Positive Net Absorption (2011 YTD): Airport (197,000 SF), Downtown (325,000 SF), Henderson (234,000 SF), Northwest (31,000 SF), Southwest (342,000 SF)

Negative Net Absorption (2011 YTD): East Las Vegas (-263,000 SF), North Las Vegas (-386,000 SF), West/Central (-294,000 SF)

Lo and behold, we're seeing more positive net absorption in the expensive parts of town than in the inexpensive parts of town. Two exceptions pop out, though. Downtown is seeing big positive net absorption in a fairly reasonably priced part of town, but much of this is due to the completion of the Las Vegas Metropolitan Police Department's new headquarters, which is owned by a private development entity and leased to the LVMPD. The other exception seems to be the Northwest submarket - pretty expensive, but fairly weak net absorption. This, however, may be more of a case of zombie properties, in particular office product owned by General Growth Properties, being unable to compete with other product for tenants.

In the near term, pricing still seems to be a major concern of businesses. There's still plenty of recession to go around, and everybody wants to make it through to the other side. Still, location and age of product clearly play a role in the desirability of space, and though newer properties are more expensive than average, they are still quite affordable compared to rates they were asking two or three years ago. Apparently, tenants are taking the opportunity to move up in the world.

Tuesday, February 21, 2012

The Winter of Our Discontent

For the past three months, the arrow has been pointing down on my Southern Nevada CRE Index, indicating a chilling of the economic climate in Southern Nevada since things ramped up a bit in mid-2011. While most measures still look pretty good when compared to one year ago, the index seems to be predicting at least one, maybe two quarters of lackluster performance for commercial real estate.


Looking at 3-month rolling averages in December on a year-over-year basis, we find the New Home Sales are flat (and disappointing), as is commercial occupancy (effectively flat since Jun 2010). All other measures show improvement year-over-year, with the biggest improvements being in the Gaming Revenue Index (3 point climb), New Residents Index (5 point climb) and Taxable Sales Index (7 point climb).

So, where are the jobs? Although the economy is moving now, it doesn’t appear to be hitting escape velocity. The Employment Index was up by one point, but remains in the same range it has been in since July of 2009. No major drop, but no real climb.


Of course, not all employment sectors are experiencing the same distress. On a year-over-year basis, the Financial Activities sector has taken over the top spot in job losses from Construction, which, by the way, is back to being a “job loser” after showing a little pickup in mid-2011. Wholesale and Manufacturing have also gone over to the dark side, leaving the immediate future of the industrial market looking gloomy. Retail is flat in terms of jobs – and this is a key sector, given how much the economy depends on consumer spending. Retail showed some improvement last year in terms of jobs, but the fourth quarter – the big holiday quarter – was flat, and that leaves 2012 in question. On the office side, the aforementioned trouble in the Financial Activities sector is evened out with job gains in Professional & Business Services and Health Care & Social Assistance. Office might not have too bad a quarter to kick off 2012, but it won’t be anything to write home about.

At the moment (and given how the numbers bounce around, "at the moment" is the best I can do prediction-wise), I predict a poor showing in the first quarter of 2012, with perhaps a slight improvement in the second quarter to give commercial real estate a fairly “meh” first half of 2012. While there has been some crowing over the “improving” job numbers nationally, the fact is that fewer people are working and incomes are not on the rise. Much of the nation’s success has been in the manufacturing sector from, believe it or not, exports. Given the fragile international economy and potential problems in Europe, China and Japan, a manufacturing export economy does not appear to provide a stable foundation for predicting good times ahead. The second half of 2012 may be an improvement over the first half, or it may be its identical twin. If you’re in the market to buy good properties and hold them, you’re probably okay. If you’re a landlord looking for a speedy resolution to your problems, you’re probably out of luck. If you’re a tenant, the market is still yours, and though a few properties have seen their asking rents rise, the majority are still struggling.

Wednesday, February 8, 2012

The Looming Shadow of CMBS

Kevin D. Williamson of the National Review just wrote a piece on the looming CMBS bonanza/Armageddon awaiting us all in 2012. As he points out:

"In New York City alone, there’s about $70 billion worth of commercial mortgages — some of which have been sold off as mortgage-backed securities, naturally — coming due this year. The national total is more than $150 billion, or a bit more than 1 percent of U.S. GDP."

You can read the entire article HERE.

Southern Nevada is, of course, no stranger to the world of distressed commercial real estate. In fact, we're probably in close competition with Sacramento for the honor of being the poster child of distressed commercial real estate. I've been tracking the area's distressed CRE since Q3 of 2009, when we had 4.1 million square feet of distressed space, most of it retail. In Q1 of 2012, we've jumped to 15.4 million square feet of distressed space, most of it now in the industrial sector.


The growth was, of course, astounding early in the recession, but has since calmed down to a trickle.


What we're now waiting to see is ... how will things shake out in 2012. Sales of distressed space had a big boost in the second quarter of 2011, notably after Auction.com's auction of around twenty CRE properties. Auction.com has another auction set for a couple weeks from now, and that might produce the same jolt to the system.

We had better hope that it does. After just one month of Q1, 2012, distressed space has grown by 4.9 percent. If we continue at that rate, we will see the gradual slide in distressed growth make an unwelcome U-turn. If distressed space keeps mounting at the same rate, Y-O-Y growth for the first quarter of 2012 will be in the neighborhood of 16 percent, the worst number we've seen since the first quarter of 2011, and the first increase

How will this potential flood of CMBS affect the local commercial market? It will drive the value of real estate down even further than it already has, which has the perverse side effect of pushing properties that otherwise would be in decent shape underwater in terms of their loan-to-value ratio, thus perpetuating the cycle. As these properties are snapped up by canny investors, they'll be able to undercut their competitors on rent, which to date is proving the key factor in many of the leases being signed these days.

In a nutshell, the cycle of re-valuing commercial real estate is not over by a long shot. You have to forgive property owners for thinking that the 50 percent plus haircut they've taken on the value of their properties has to represent the end of the cycle, but the looming wave of foreclosures and short sales suggests that it is not. Commercial real estate in Southern Nevada is already selling at below replacement cost, and it looks like those values, and prices, are going to be compressed a bit further before all is said and done. The lesson here - there are deals to be had in Southern Nevada, but only if you want to hold them for the long term. While quick flips are not impossible, especially for properties bought at an absolute premium at an auction, they will probably be the exception rather than the rule for the next few years.

Thursday, February 2, 2012

Like Molasses in January

I know, it's supposed to be February ... but the going has been slow this January, with strong indications that January was a negative month for Southern Nevada commercial real estate.

December employment numbers finally popped, and the year turned out to a bit weaker jobs-wise than November had made things appear. Looking at my database activity in January, this does not come as a surprise for me.


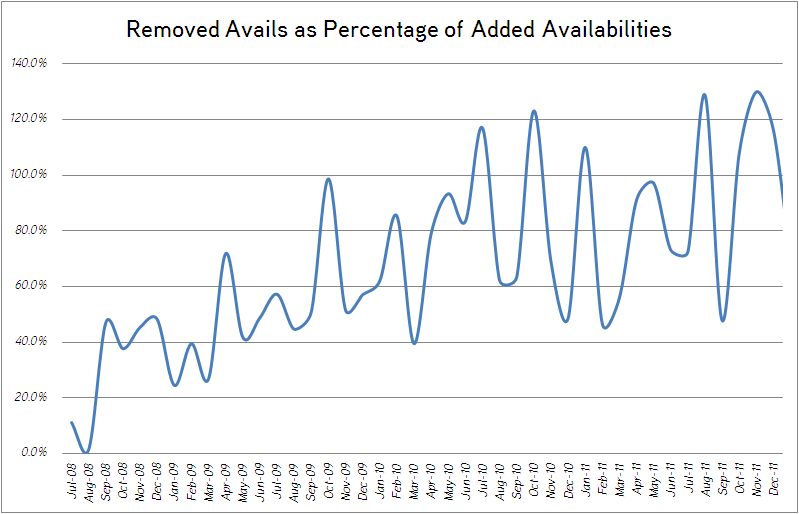
Overall, the trend is still positive, but the climb is so gradual that it isn't hard to miss it. The graph above shows the number of avails removed from the database as a percentage of the number of availabilities added. Now, this is not scientific by any means because it doesn't take into account the size of the leases, but it does give an idea of which direction the market is going. I can say, as they guy who has to enter and remove all of these records, that the trend right now is the new availabilities are bigger than the removed availabilities.

You can see that there have been a few months (July 2010, October 2010, January 2011, September 2011 and November to December 2011) where availabilities removed exceeded availabilities added. Between Jul 2008 and July 2010, there was a pretty steady improvement in this number. Once we hit mid-2010, though, the needled started jumping, so to speak, as though there was an earthquake. Several strong months, several weak months. This is one of factors that is making predicting the next 12 months of the Southern Nevada commercial real estate sector's performance difficult.

If we drill down a bit, we can see how different types of availability are shaking out.


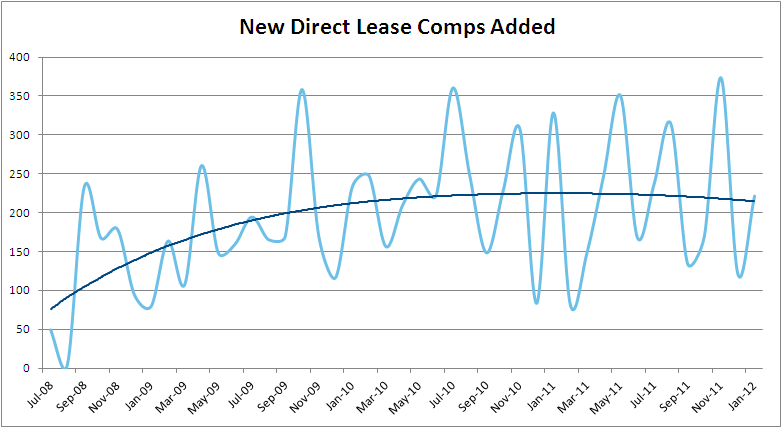
The number of direct lease comps added to the database showed distinct improvement in 2008/2009. Since then, the trend has flattened out, and January 2012 has bent things in the wrong direction. Perhaps February numbers will change that, but for now, it looks as though leasing activity has "topped out".


The picture is more promising for sales comps. They hid a nadir in early 2009 and have improved since then, but still we see the gaps between "good months" and "bad months" getting very wide in 2011.


What does it all mean? That's the big question. Either things are mellowing out for a month or two before they begin to climb again, or 2011 was our big "recovery" year and 2012 is going to come in a bit weaker. Personally, I believe it is the former rather than the latter, but I'm not counting the latter out.

February will give us a better idea of what lies ahead in 2012. If February is weaker than January, then all bets are off on 2012 being any stronger than 2011 and you can probably flip a coin on whether any given product type posts minimal negative or positive net absorption by year's end.

On the other hand, if February reverses January's course, then it appears that we're in a gradually improving market in 2012. Let's hope for a strong February! Either way, things have grown quite volatile, so keep your seat belt fastened.

Tuesday, January 24, 2012

Digging Into the Office Data

Aside from my normal analysis for the quarterly reports, most of my analysis comes about due to my mind wandering while I'm updating my database (a three to four hour task every day of the week).

Yesterday, I began to wonder about where the net absorption had been going over the last decade in the office market - sort of looking back to look forward.

So, today I put together some numbers comparing the share of office net absorption claimed by the different classes of product and the different submarkets here in Fabulous Las Vegas (or Fabulous Southern Nevada, to be more precise).

Share of Net Absorption by Class, 2001-2011


No surprise here. Southern Nevada is a third tier office market that leans heavily on its Class B and Class C product. If we look at this same graph, but leaving out the last 4 years of recession-era data ...

Share of Net Absorption by Class, 2001-2007


... we see that over the last four year a tiny shift from Class C to Class A and Class B product has occurred, most likely a result of lower rents allowing businesses to "move up in the world" and take better space.

Share of Net Absorption by Submarket, 2001-2011


The recession has been felt most keenly by the older submarkets of East Las Vegas and West Central, with both turning in negative net absorption for the decade. The Southwest and Henderson submarkets appear to have been the key benefactors of this flight.

Share of Net Absorption by Submarket, 2001-2007


Screening out the recession data, we see that East Las Vegas and West Central turn positive, but not by much. More interesting, perhaps, is the switch between Henderson and the Northwest submarket. Pre-recession, Northwest was firing on all cylinders. Unfortunately, a great deal of its office space was caught up in the restructuring of General Growth Properties, and languished in the form of "zombie buildings", unable to offer tenant improvements and thus compete with non-distressed office space elsewhere.

Henderson has done well, but they're about to lose a significant tenant in the form of Zappos.com, which is moving to the Downtown submarket by 2014.

Moving forward, one might want to focus on Class B and Class C office product in the Southwest and Northwest submarkets, and perhaps in the Airport and Henderson submarkets as well. All of these classes of office have fairly high vacancy rates in these submarkets at the moment ...


... so there's probably little need for development over the next few years. Class B product in the Airport submarket looks the most promising, but it is worth remembering that there isn't much vacant land on which to develop large office products in the Airport submarket - most of that sort of development will probably be shifted south into the western reaches of the Henderson submarket if it occurs at all.

I'll leave you with the following graph, which tracks quarterly office net absorption by class over the past decade. It's been quite a roller coaster ride, but at least things look to be heading up, assuming we can weather the deleveraging storm on the horizon.


Tuesday, January 17, 2012

Office Dead Zones!

Last week we took a look at where all of the distressed office space was located in Southern Nevada, and discovered no real pattern.

Today, it's time to take a look at office activity in 2011 and seek out the dead zones - those areas of town that didn't show much, if any, lease or sales activity (i.e. gross absorption).

This map plots two different sets of data.

The first, in the large, grey dots, are the locations of available office spaces in Southern Nevada in 2011.

The second, in the smaller, yellow dots, are the locations of office buildings that saw their total square footage of available space decrease between the fourth quarter of 2010 and the fourth quarter of 2011. If I get some more spare time, I'll do this exercise on a quarter-by-quarter basis, but this map will have to do for now - and it does show the location of about 3.3 million square feet of lease and sales activity.

Click the image for a magnified view.

So, what do we learn?

At first glance, it seems as though there is no big pattern. Businesses are taking space all over town, and this probably indicates that the key driver is not location or age of property, but price. We are probably seeing a flight to affordability, rather than a flight to quality.

With a closer inspection, though, we do see a few small dead zones.

The first dead zone is on the southern portion of Fort Apache, near the "Curve" of I-215. While these projects are fairly easy to access via I-215, they appear to be just far enough off the beaten path to be struggling.

There are avails in North Las Vegas that are having trouble competing, but North Las Vegas, on the whole, appears to be doing fairly well in terms of leasing activity.

More interesting is the dead stretch on west Cheyenne, between US-95 and I-215. This is Summerlin territory, and traditionally highly sought after. This may bolster the case for "flight to affordability", but might also show the impact of distressed space on leasing. A few projects in this area were up in limbo until recently, and unable to effectively compete for tenants.

The final dead zone - and not a surprise - is located on Lake Mead Blvd in Henderson. It's a bit out of the way, and not an area known for its office product.

Other than those few zones, it appears that leasing and sales are taking place wherever there is space available - assuming the price is right.
Related Posts Plugin for WordPress, Blogger...